Health insurance in Argentina for Australians
Australian Medicare does not cover care in Argentina. Arrange travel insurance before departure, then compare written prepaga (private health plan) quotes. National hospitals require insurance or advance payment from many non-permanent foreign residents for routine care.
Updated · 7 min read
The short version
- Medicare abroad
- Australian Medicare does not pay for overseas care; Argentina has no Australian reciprocal healthcare agreement, September 2026.
- National hospitals
- Resolution 1066/2026 began applying in August 2026; habitual care for non-permanent foreigners requires insurance or advance payment.
- OSDE benchmark
- Plan 210 advertised at ARS 314,922/month (about AUD 295.30) for age 30, September 2026; third-party comparison, not an insurer quote.
- Waiting rules
- Law 26.682, art. 10: no waiting period for mandatory medical programme services; other waits must be stated and approved.
Australian Medicare does not cover treatment in Argentina, and Argentina is not on Australia’s reciprocal healthcare-agreement list. Buy travel medical insurance before leaving Australia, then obtain a written quote for a local prepaga (private prepaid health plan) such as OSDE, Swiss Medical or Galeno before relying on it for routine care.
What public care is available after the 2026 change?
An emergency cannot be held up for an administrative payment check because of immigration status. For habitual, non-emergency treatment at nationally administered hospitals, the August 2026 procedure under Resolution 1066/2026 requires a foreigner without permanent residence to present health insurance or pay in advance. The treating clinician decides whether the condition is an emergency; subsequent care can be billed after the emergency phase. These national-facility rules do not establish the billing policy for every provincial or municipal hospital.
Permanent foreign residents have the same public-healthcare access basis as Argentine citizens under the amended Migration Law. Temporary residents and visitors should budget for routine treatment rather than assume public care is free. If you are arranging Argentine residence as an Australian, allow for the period before your final status is issued when planning medical costs.
Australia’s Services Australia also says Medicare does not cover you while overseas. Argentina is absent from its reciprocal agreement country list. The Medicare rules when leaving Australia cover the Australian side; no Medicare card will pay an Argentine private hospital bill.
How does a prepaga work?
A prepaga is a paid local health plan. You choose a plan and pay its monthly cuota (premium); the insurer publishes a cartilla (network directory) of contracted doctors, clinics and hospitals, and individual services or plan tiers can have copayments. Before paying, ask the provider for the plan’s written premium and cartilla for the specific hospital site and specialist you expect to use. A hospital group may have a main campus and a separate emergency address; inclusion of one site should not be assumed to include the other.
OSDE publishes plan tiers 210, 310, 410, 450 and 510, and says the price varies with the plan, age, family composition and employment/contribution status. Swiss Medical and Galeno publish plan and individual-quotation pages. A self-purchased prepaga should not be confused with an employer-linked obra social (social-health cover): ask your employer which scheme and contributions apply if you will work locally. Do not assume Australian private hospital insurance pays local Argentine claims on the same terms.
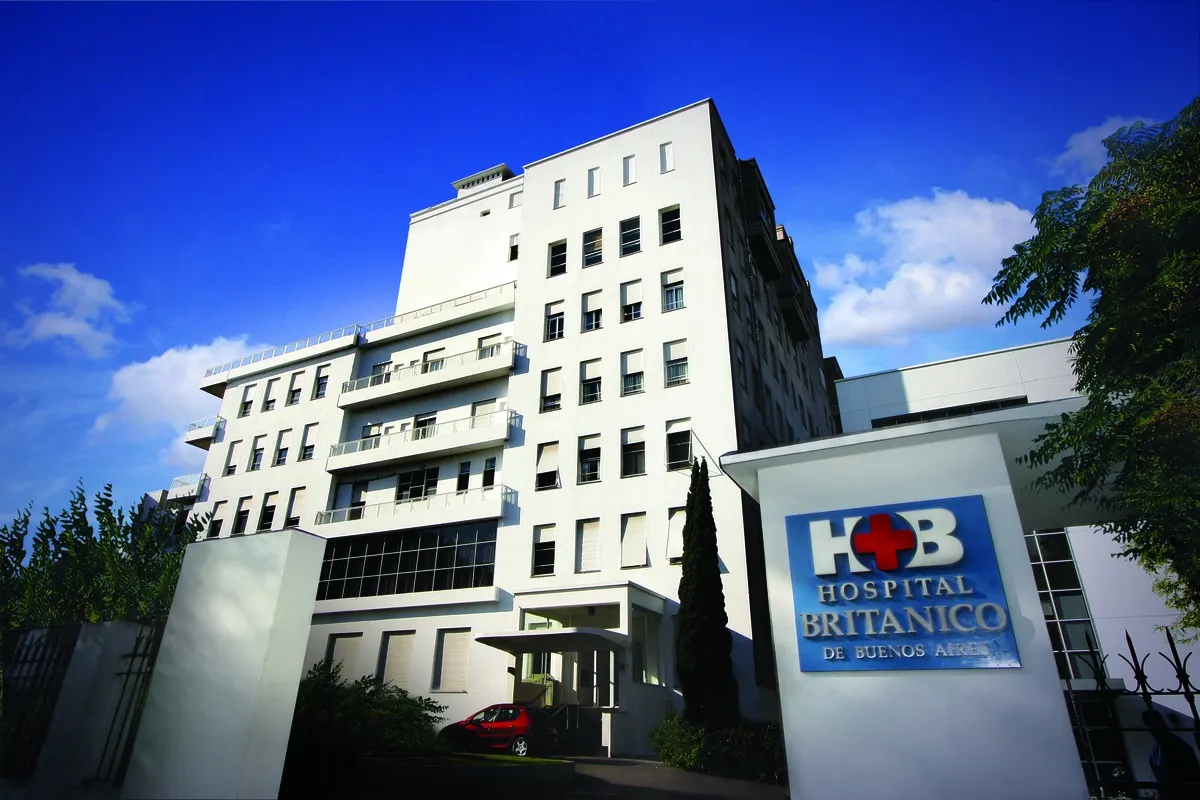
For a concrete network comparison in Buenos Aires, Hospital Británico is at Perdriel 74; Hospital Alemán lists its main campus at Av. Pueyrredón 1640 and its emergency centre at Beruti 2557; Hospital Italiano’s central site is at Tte. Gral. Juan Domingo Perón 4190. These are comparison points, not endorsements or a claim that any named plan covers every service there. The Buenos Aires hospital guide helps separate an emergency destination from a routine appointment.
What does private health insurance cost in September 2026?
| September 2026 example | Monthly premium | AUD context | What it establishes |
|---|---|---|---|
| OSDE Plan 210, individual aged 30, quoted by comparison service PrepagaYa | ARS 314,922 | About AUD 295.30 at Wise’s indicative AUD 1 = ARS 1,066.43 mid-market rate | Commercial comparison benchmark only; not an OSDE invoice, a guaranteed future premium or an equivalent Australian policy. |
| Swiss Medical individual plan | Individual quote required | No verified comparable AUD premium | Choose plan, age, location and network before comparing. |
| Galeno individual plan | Individual quote required | No verified comparable AUD premium | Request the same coverage details and family composition used for the other quotes. |
Compare a written ARS quote with the regulator’s provider-declared plan tariffs. Age, location, contributions and copayments affect the price. The AUD conversion at the cited mid-market rate does not include your bank’s charges; the commercial example is not a quote for Swiss Medical or Galeno.
Do waiting periods or pre-existing conditions affect cover?
Article 10 of Argentina’s Prepaid Medical Companies Law, Law 26.682, prohibits waiting periods for services in the Programa Médico Obligatorio (PMO, mandatory medical programme). Waiting periods for other services must be stated clearly in the contract and approved by the regulator. Ask for the plan-specific contract rather than accepting an informal assurance that everything starts on day one.
The same article says a declared pre-existing condition alone cannot be grounds to reject admission. The applicant declares pre-existing conditions; a justified differential premium needs regulator approval. Disclose a condition accurately on the application and get the proposed price and applicable cover in writing before replacing your travel policy. That statutory admission rule is not a promise of an unchanged ordinary premium or of automatic coverage for every optional service.
What insurance should cover the arrival period?
- Purchase travel medical insurance before departure with medical evacuation and repatriation terms that cover your full route, including stopovers. Smartraveller warns that DFAT will not pay medical or evacuation bills and that private facilities may demand cash before treatment.
- Read the policy’s conditions for the activities you will actually do. Pre-existing conditions, snow sports and motorcycling need explicit cover where relevant. Check the expiry date against your planned arrival and the start date of any Argentine plan rather than assuming they overlap.
- Request local quotes after establishing what you can enrol in. Give each provider the same age, location and household details. Ask about foreign identity documents, start date, written tariff, network, copayments and waits for services outside the PMO.
- Keep travel cover until your local policy is active and its limits are understood. A prepaga network is not, by itself, overseas medical-evacuation cover. Record the emergency contact number and an in-network emergency site for your exact tier.
For a medical emergency in Argentina call 107; 911 is another emergency number. Hospital bills and insurer authorisation can be handled after emergency assessment, but the emergency exception does not make all later care free.
Common questions
Does Australian Medicare cover treatment in Argentina?
No. Medicare does not cover care overseas, and Argentina is not an Australian reciprocal-healthcare-agreement country.
Can I go to a public hospital without Argentine residency?
Emergency assessment cannot be delayed for an administrative payment check. At nationally administered hospitals, routine care for a foreigner without permanent residence requires insurance or advance payment under the August 2026 procedure; later emergency-related costs can still be billed.
How much is an OSDE plan in Argentina?
A September 2026 commercial comparison listed OSDE Plan 210 at ARS 314,922 a month (about AUD 295.30 at the cited mid-market rate) for an individual aged 30. Your written premium depends on the chosen plan and personal details.
Can a prepaga refuse me because of a pre-existing condition?
Law 26.682 says a declared pre-existing condition alone cannot be a reason to refuse admission. A regulator-authorised differential premium may apply; disclose the condition and obtain the applicable terms in writing.
Is there a waiting period for private medical cover?
Law 26.682 prohibits waiting periods for mandatory PMO services. Waiting periods for other contracted services must be stated and approved, so read the exact plan contract before cancelling travel cover.
Is travel insurance enough for a long move?
Travel insurance covers its stated term and conditions, so it should bridge arrival until an appropriate local plan is active. Check evacuation, repatriation and any pre-existing-condition or activity exclusions before departure.
Sources
- Services Australia: Retiring overseas · Medicare does not cover overseas care.
- Services Australia: About reciprocal health care agreements · Argentina is not listed.
- Boletín Oficial: Resolución 1066/2026 · National-facility habitual-care procedure.
- Ministry of Health: Los hospitales nacionales comenzarán a cobrarles a los extranjeros no residentes · Emergency triage and subsequent charges.
- Smartraveller: Argentina · Insurance and medical evacuation advice; emergency numbers.
- Argentina.gob.ar: Ley 26.682, artículo 10 · Waiting periods, pre-existing conditions, regulator-authorised differential premium; official law text retrieved September 2026.
- OSDE: Precios de cada plan · Plan tiers and individual premium variables.
- Swiss Medical: Planes · Individual plan quotation.
- Galeno: Planes · Plan listings.
- PrepagaYa: OSDE · Third-party September 2026 benchmark for age 30, not an insurer invoice.
- Superintendencia de Servicios de Salud: Valores de planes · Provider-declared tariff lookup.
- Wise: AUD to ARS rate · September 2026 indicative mid-market conversion only.
- Hospital Británico: Cómo llegar · Hospital location.
- Hospital Alemán: Sedes · Main and emergency site locations.
- Hospital Italiano de Buenos Aires · Hospital central site.